Help Center
Deliver to:
Ship to
Currency
USD (US Dollar)
Save
Your Cart
Your quote requests is empty.
Welcome back! If you had Quote requests items in your Shopping cart, we have saved them for you. You can Sign in now to see them, or whenever you're ready to check out.
Total $0.00
View Cart

EU Tax Reform 2026: Abolition of Duty Exemption for Low-Value Goods (≤ EUR 150)

Last updated on Jul 27, 2026

2026 EU Customs Tariff Regulation Updates
Quick 30-Second Overview

Effective July 1, 2026

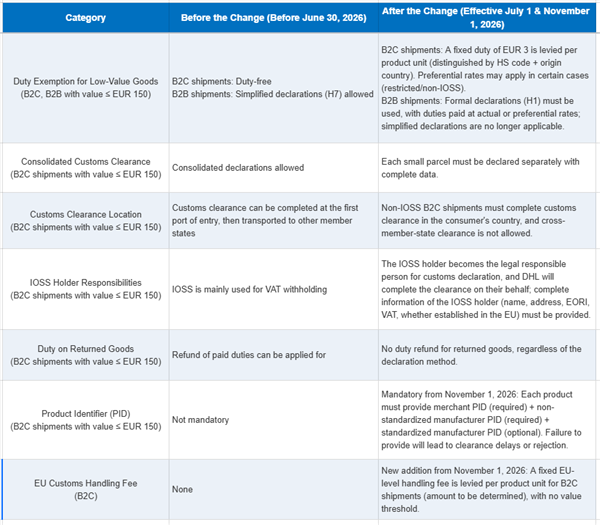
  • B2C shipments (value ≤ EUR 150): The original duty exemption policy is revoked, with a fixed duty of EUR 3 charged per piece of goods
  • B2B shipments: Simplified H7 customs declarations will no longer be accepted, and formal full H1 customs declarations become compulsory

Effective November 1, 2026

  • Submission of Product Identifier (PID) data is mandatory for all B2C shipments
  • A new unified EU-wide customs administrative fee will be imposed

General Overview of EU Customs Regulatory Changes

Against the backdrop of a massive influx of low-value e-commerce parcels into the EU, accompanied by prevalent goods undervaluation and chaotic origin declaration issues, the EU has formally enacted the EU Customs Reform (EUCR). A set of comprehensive regulatory revisions will be rolled out in phases.

Revised Rules Taking Effect on July 1, 2026

1. Cancellation of duty exemption for low-value goods (≤ EUR 150)

  • This rule applies to goods valued at no more than EUR 150 shipped from non-EU27 countries to all 27 EU member states.
  • For B2C shipments: A flat rate duty of EUR 3 will be levied on each individual product unit (distinguished by 6-digit HS code plus country of origin).
  • For B2B shipments: Simplified H7 declaration mode is banned. Businesses must submit standard formal H1 customs declarations, with duties calculated in accordance with normal or preferential tariff rates.

2. Restrictions on consolidated customs clearance

Consolidated clearance is generally prohibited for non-IOSS B2C parcels worth ≤ EUR 150; each individual small parcel must go through separate customs declaration procedures.

3. Mandatory rule for customs clearance location

Non-IOSS B2C parcels valued ≤ EUR 150 must complete customs clearance in the destination country of receipt. Cross-clearance at the first entry port of another EU member state is no longer allowed.

4. Expanded legal liabilities of IOSS registrants

IOSS holders are identified as declarants and shall bear full legal liabilities for import customs clearance. Although DHL will handle clearance formalities on your behalf, the following documents and information must be provided completely:

Full legal name and registered address of the IOSS entity

Proof confirming whether the enterprise is established within the EU territory

Corresponding EORI number and VAT ID number (if applicable)

5. Termination of duty refund for returned goods

No duty refunds will be processed for returned B2C shipments valued ≤ EUR 150, whether declared via formal or simplified channels. The existing VAT refund policy stays unchanged.

Revised Rules Taking Effect on November 1, 2026

All B2C imported parcels entering the EU27 territory are required to upload PID information and pay the newly introduced EU unified customs handling fee.

1. Mandatory Product Identifier (PID) provision

  • Merchant internal product ID (required item)
  • Non-standard manufacturer coding (required item, e.g. internal SKU, item serial number)
  • Standard public manufacturer coding (optional item, e.g. GTIN, MPN, EAN barcode number)

2. EU Unified Customs Handling Fee

A fixed per-unit customs handling fee regulated at the EU level will be collected. The specific charge standard has not yet been officially announced. This fee is independent of the local customs clearance fees separately collected by individual EU member states such as France and Romania.

Subsequent Policy Deployment (2028 onwards)

The EU will gradually oblige all trading merchants to access the EU Customs Data Hub and set up a centralised EU customs management authority. Relevant detailed specifications will be released via official notices in due course.

Impacts & Required Countermeasures for Your Business

Core Compliance Requirements to Guarantee Smooth Customs Clearance

The EU’s large-scale adjustment on tariff policies for low-value cross-border e-commerce parcels is still undergoing fine-tuning, Justway makes every effort to learn in real time and obtain more official information.To avoid clearance delays, shippers must furnish complete and accurate commercial invoice information for all consignments, including detailed product descriptions, 6-digit HS codes, country of origin and corresponding PID data.

Mandatory materials for B2C shippers & IOSS holders (effective July 1, 2026)

  • Full enterprise name and official address
  • EORI (Economic Operators’ Registration and Identification) number
  • VAT identification number
  • Proof of EU local establishment status; if not registered in the EU, provide information of your appointed EU Importer of Record (IOR) or EU authorised representative
  • Clear marked retail prices on commercial invoices and import declarations for all B2C commodities
  • Valid consignee email address and mobile phone number to ensure smooth communication with customs authorities
  • We recommend shippers assess the impacts of the Anti-Abuse Clause (UCC/IA Article 243(5)) on your imported goods in advance.

Mandatory PID submission rules for all B2C shipments (effective November 1, 2026)

  • Merchant self-defined product ID (required)
  • Non-standard manufacturer internal number (required)
  • Public standard manufacturer code (provide if available)

If you have any inquiries concerning the new EU Customs Reform provisions, please get in touch with your dedicated justway account manager for professional support to secure stable operation of your cross-border business.

*Policy terms are subject to real-time official updates, and justway will issue supplementary guidance accordingly.

Interactive Q&A

The new EU tariff regulations are soon to be enforced — are your business fully prepared?

Have you supplemented and improved your PID data fields in advance?

Have you formulated corresponding pricing solutions to offset the EUR 3 fixed duty per product?

Have you finished operational adjustments responding to the ban on consolidated parcel clearance?

Feel free to share your practical experience and existing challenges in the comment area; our customs specialists will respond to your questions.


2026 EU Customs Reform (EUCR) Takes Effect: Answers to Your Most Pressing Questions